Galaxy.jpg

Risk Advisory and Due Diligence

Your Lifeline in a Risky World

RISK ADVISORY

Independent Perspective on Complex Financial Risk

CMRA advises boards, financial institutions, asset managers and institutional investors on complex questions of portfolio risk, stress testing, valuation and risk governance.

For more than three decades, we have helped clients challenge assumptions, identify overlooked exposures and strengthen risk-management decisions before those assumptions are tested by the market.

30+ Years of Risk Advisory Experience
100+ Clients Advised
6 Continents of Client Experience
THE CMRA PERSPECTIVE

The greatest risks are often the ones the model was not built to see.

Risk measures are essential. But they depend on assumptions about markets, liquidity, correlations, volatility and behavior that may change precisely when they matter most.

CMRA brings an independent perspective shaped by decades of work across trading, portfolio management, valuation, governance, market crises and complex financial disputes.

We ask not only what the risk framework measures — but what it may be missing.

INDEPENDENT RISK REVIEW

Independent Risk Review & Stress-Test Challenge

Who stress tests the stress test?

Stress testing is only as good as the assumptions behind it. CMRA independently evaluates the scenarios, assumptions and models institutions use to understand portfolio risk.

The objective is not to create another risk model. It is to determine whether existing analysis captures the risks that matter — and whether apparently reasonable assumptions remain credible under severe market conditions.

01

Stress Scenarios & Assumptions

Are the scenarios severe enough, relevant enough and built on assumptions that remain credible when markets behave differently than expected?

02

Liquidity, Leverage & Margin

How do funding needs, collateral demands, leverage and market liquidity interact when positions move rapidly against the portfolio?

03

Models, Valuation & Hedge Effectiveness

Which model inputs, valuation assumptions and hedging relationships may become unreliable under changing or stressed market conditions?

ALSO CHALLENGED
Correlation & Cross-Asset Behavior
Volatility & Volatility Surfaces
Interest-Rate & Mortgage Risk
Concentration & Tail Risk
Out-of-Sample Risk

The question is not only whether a portfolio survives the scenario that was modeled — but whether the right scenario was modeled in the first place.

RISK GOVERNANCE & BOARD ADVISORY

Effective Risk Management Begins with Governance

What risks keep the board up at night?

CMRA helps boards, investment committees and senior management determine whether the risks they care about most are actually reflected in the institution’s risk framework, limits, scenarios and reporting.

Our work focuses not only on formal governance structures, but on whether responsibility, challenge, escalation and decision-making function effectively in practice.

01

Governance & Independent Oversight

Review board and investment-committee oversight, the role and independence of the risk function, CRO responsibilities, committee structures and escalation processes.

02

Risk Appetite, Policies & Limits

Translate risk strategy into practical Risk Appetite Statements, policies, limits and escalation frameworks that can guide decision-making across the institution.

03

Board Reporting & Risk Education

Assess whether management reporting gives boards and senior executives a decision-useful view of material risks and help translate complex market and portfolio issues into clear board-level information.

THE BOARD LENS

Good governance is not defined by the number of policies. It is defined by whether the right questions reach the right decision-makers in time.

  • Are responsibilities and decision rights clear?
  • Are risk limits aligned with the institution’s actual risk appetite?
  • Do board concerns appear in stress scenarios and management reporting?
  • Are breaches and emerging risks escalated early enough?
  • Is the independent risk function positioned to challenge business decisions effectively?
~140

CMRA’s risk-governance work has included broad industry benchmarking, including a Risk Governance Survey covering approximately 140 financial institutions.

VALUATION, MODELS & COMPLEX PORTFOLIO RISK

Complex Portfolios Depend on Assumptions That May Not Be Obvious

Risk can be hidden in the assumptions behind the price, the model or the hedge.

CMRA independently reviews valuation methodologies, model inputs, sensitivities and portfolio assumptions with particular attention to the limitations that may become material under changing or stressed market conditions.

Our work combines quantitative review with market judgment, governance and practical portfolio experience to assess how complex exposures may behave when normal relationships begin to break down.

01

Models & Valuation

Pricing methodologies, model inputs, sensitivities, independent marks, valuation policies and model governance.

02

Derivatives & Hedging

Options, swaps, futures, volatility exposure and whether hedging strategies continue to perform as intended under stress.

03

Liquidity, Collateral & Counterparty

Funding, margin, collateral values, counterparty exposure and the interaction between liquidity needs and market moves.

04

Complex & Less-Liquid Assets

Structured credit, mortgage-backed securities, model-dependent investments and other assets where pricing and liquidity can become especially uncertain under stress.

EXPLORE CMRA MARKET & PRODUCT EXPERIENCE

CMRA’s advisory, regulatory and expert work spans complex instruments and asset classes across global capital markets. Explore selected areas of deeper CMRA experience below.

Independent review asks not only whether a model is mathematically sound, but whether its assumptions remain economically credible when market conditions change.

RISK DUE DILIGENCE & BEST-PRACTICE REVIEW

Independent Review Beyond the Questionnaire

Good due diligence asks not only what the policy says, but what actually happens in practice.

CMRA helps institutional investors , asset managers and financial institutions evaluate investment, operational and risk-management practices through an independent capital-markets lens.

Our work combines quantitative analysis with review of governance, controls, valuation, strategy, documentation and organizational practices.

THE QUESTION

Is there a gap between the risk framework described on paper and the way risk is actually managed?

01

DDQ Design & Review Frameworks

Design and refine due diligence questionnaires and review frameworks tailored to investment strategies, organizations and risk profiles.

The objective is to move beyond generic questions and focus attention on the investment, operational, governance and risk issues most likely to matter.
02

Independent Due Diligence Reviews

CMRA has conducted due diligence on alternative investment managers, portfolios, strategies, transactions and financial-services businesses.

Reviews may address investment strategy, valuation, operations, governance, controls, documentation, collateral and risk-management practices.

03

Investor Training & Independent Challenge

CMRA trains institutional investors to ask more targeted questions, evaluate manager responses and identify weaknesses that may not be apparent from standardized disclosures.

We also help investment and risk teams develop a more disciplined framework for challenging assumptions, controls and manager representations.

THE BEST-PRACTICE LENS

Independent review should test both the framework and the evidence that the framework works.

Investment & Portfolio Risk
Governance & Independent Controls
Valuation & Pricing Practices
Policies, Procedures & Escalation
Risk Reporting & Transparency
Peer Practices & Benchmarking
Manager Representations vs. Practice
Gaps in Controls or Implementation

CMRA’s due diligence work is informed by broader experience in risk governance, valuation, derivatives, portfolio risk and financial disputes — providing context that a checklist alone cannot supply.

WHO WE ADVISE

Senior-Level Risk Advice Across Financial Institutions

Different institutions face different risks — but all benefit from independent challenge.

CMRA works with organizations across global capital markets, adapting its analysis to the institution, portfolio, governance structure and decisions at hand.

Our role is not to replace internal investment or risk teams, but to bring an independent perspective to the questions that matter most.

A COMMON THREAD

The most useful risk advice begins with the institution’s actual exposures, decisions and governance — not with a generic framework.

HOW CMRA WORKS

Senior-Level, Project-Based Advice

Independent advice should add perspective — not another layer of bureaucracy.

CMRA engagements are designed around the specific risk questions facing the client rather than a standardized consulting methodology.

Work is conducted at a senior level and tailored to the institution, portfolio and decisions at hand.

01

Understand the Risk Question

Discussions with boards, CIOs, CROs and investment or risk professionals establish the decisions, concerns and exposures that matter most.

02

Independently Challenge

CMRA reviews assumptions, models, policies, reporting and market practices through an independent capital-markets lens.

03

Identify Findings & Gaps

Analysis focuses on material weaknesses, overlooked exposures and practical opportunities to strengthen the existing framework.

04

Deliver Actionable Advice

Findings and recommendations are presented in clear, decision-useful language for senior management, investment committees and boards.

OUR ROLE

CMRA works alongside existing professionals, providing independent challenge where an outside perspective can improve the quality of the decision.

TYPICAL ENGAGEMENT OUTPUTS
Independent Risk Assessment
Stress-Test Challenge
Governance & Policy Recommendations
Valuation or Model Review
Best-Practice Benchmarking
Board or Senior-Management Presentation
CMRA'S GALAXY OF RISKS™

Risk Is Broader Than the Risks That Are Easiest to Measure

The most important risk may not be the one already captured in the standard report.

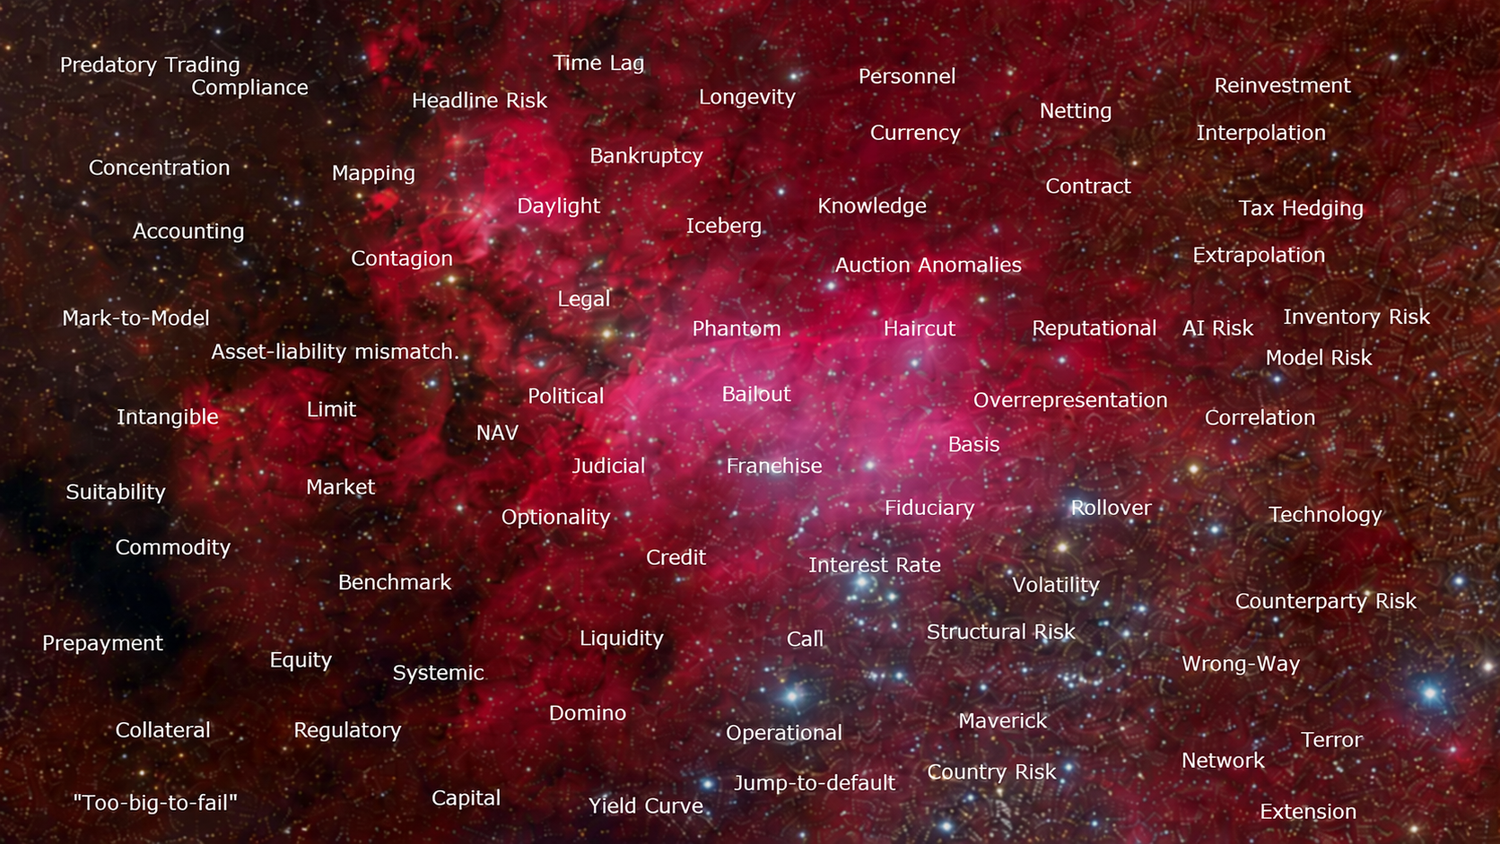
CMRA’s Galaxy of Risks™ reflects a broader view of financial risk, extending beyond traditional market and credit measures to include risks arising from assumptions, liquidity, complexity, organizational structure and market behavior.

The framework is intended to broaden the questions institutions ask when evaluating whether a portfolio, strategy or risk-management process has been viewed from enough different angles.

THE CMRA VIEW

What is missing from the risk framework may matter as much as what has already been measured.

CMRA Galaxy of Risks showing a broad range of financial, market, operational and emerging risks

CMRA's Galaxy of Risks™ illustrates the breadth of risks that may affect financial institutions, portfolios, transactions and investment strategies.

Explore Risk Management →
 

“I foresee a day . . . when risk unit allocation surpasses asset allocation as a way to decide where to place investments”
— Risk.net (February, 1999)


CMRA and its Senior Practioners have been at the Forefront of Risk Management Since the Early 80's


The liquidity crunch brought home to many investors, portfolio managers, service providers and prime brokers how sharply valuations can diverge when a portfolio becomes unexpectedly illiquid...

"I was a diehard advocate for mark-to-market, and I still believe it's the lesser of evils, but there are times when model-based pricing might make sense," said Ms. Rahl. This would of course imply that the model-based methodology was favored over mark-to-market because either market prices were stale or unavailable, or the relationship between the underlying and the proxy was weak. "The option of using such a valuation methodology would require strict checks and balances within a fund," she said.

"Marks on the collateral don't necessarily represent the price at which a trade can be unwound," said Ms. Rahl. "In some situations we have seen the exact same trades with two different counterparties being unwound at vastly different prices."

- Hedgeworld (July 2008)


Leslie Rahl says "People put too much emphasis on asset diversification and not enough on diversifying the more subtle risk factors such sensitivities to volatility, to flights to quality, to credit, etc."

- CFA Magazine (July/August 2008)


...Clearly the interests of the solvent and bankrupt parties are opposite when it comes to valuing contracts for early termination, and not surprisingly it can become contentious. Leslie Rahl, president and founder of Capital Market Risk Advisors, a risk consultancy, said that "there's almost always a difference of opinion, breakage between the value that someone thinks they're going to receive and what they do [receive]. Even if you have two [originally] matched trades you're going to take them off at different prices." In other words, what looked like two sets of perfectly offsetting positions-a perfect hedge-may turn out not to offset once quotes have been obtained and the contracts terminated.


While the quote method would seem to be objective, depending on the liquidity of the market the results can still be dubious. "I've seen bunched quotes, three bunched together at one end, and two at the other, as though there's a significant difference of opinion among dealers." As a result, even after dropping the outliers, "you can still get a mishmash," Ms. Rahl said... 

- Journal of Global Financial Markets (Spring 2002)


...Rahl began by presenting a long list of the risks facing financial companies, one that has been growing over time (see Galaxy of Risks). She used the analogy of an iceberg to illustrate the key issue faced by risk managers contemplating such a list of risks: everyone understands the existence of the iceberg, but no one knows what it looks like under the water.

Rahl pointed out that the analytical components of risk management - value at risk, stress testing, backtesting, model review, and limits - are all important.

More generally, Rahl argued that models will never capture the full "galaxy of risks." Things tend to go wrong, she warned, when people begin to believe the numbers. Clever forms of fraud, new market moves, acts of God, and regulatory surprises - to name a few - always threaten to overwhelm a models assumptions...

Rahl also cautioned against using value at risk as a worst-case scenario...

- Federal Reserve Bank of New York Economic Policy Review (January 2000)


The widely respected risk consultants, Capital Market Risk Advisors (CMRA) in New York even went so far as to label 1997 the "year of model losses". The firm attributes losses of $2.7 billion or 40% of all derivatives losses for the year to models.

- Risk.net (September 1998)


Leslie Rahl: I agree completely with the comments on the importance of stress-testing, but I guess I would go one step further. I think people are really making a mistake in not also stress-tesing their VaR models. Many people found out that their exposures with many counterparties were multiples of what the credit department thought they should be. Unfortunately, most stress-testing has been done in the market risk arena, rather than applied to the potential credit exposure. I would contend that the models aren’t nearly as bad as they might be portrayed, but that the assumptions being put into the models as well as the stress-testing of those assumptions have not received enough attention. 

- Derivatives Strategy (December 1998)


Capital Market Risk Advisors, warns that risk models based on historical default data could prove invalid for credit derivatives linked to syndicated loans

- BusinessWeek (July 1997)


Most derivative houses now provision for credit risk. But very few do so for liquidity. Leslie Rahl thinks the liquidity of underlying markets, or the lack of it, will be of increasing concern, forcing houses to provision accordingly. "In the same way people set aside reserves depending on the credit of the counterparty, I think you're going to have people set aside for liquidity. The reserve you'd set aside for a three-year US dollar interest rate swap would be quite different from CTE [Ecu Italian government bond] swaption" . . . A clearing house for OTC products could be one alternative: "I could easily envisage a clearing house in which, once a deal is done, a central margining credit-enhancement vehicle takes over."

- Risk.net (December 1992)

When an investment bank that is supposed to know better loses billions of dollars betting on subprime mortgages, you have to wonder what happened to the concept of risk management. "You can't rely on VaR as your only metric," says Leslie Rahl, president and founder of New York–based Capital Market Risk Advisors. "We recommend people use three to five different metrics. It's like a doctor ordering an X ray, an MRI and a CAT scan — they all tell you slightly different things." ...

Rahl recommends applying stress tests to see how a portfolio would react to sharp drops, market shifts, unusual situations or changes in underlying assumptions. Stress-testing models, which are included in risk systems, can reveal weaknesses that a simple VaR test misses. But Rahl says too many financial firms continue to rely mostly on VaR. Back in April 2000, Rahl's firm conducted a survey of risk practices and found that 45 percent of financial firms, including hedge funds, were not using stress tests at all. Although she hasn't updated the survey, she says she has noticed only a slight improvement since then.
 

"In risk management only about a third is quantitative," Rahl says. "A third is still a big part of the puzzle, so it is quite valuable." The remaining two thirds of the puzzle is where good risk managers earn their money. Ultimately, an accurate forecast depends on knowledge, experience and chutzpah.

- Alpha (June 2008)


Last month, New York-based consultancy Capital Market Risk Advisors released a survey on economic capital allocation. It reported the economic capital allocated by large global banks to operational and other risks (but not market risk or credit risk) ranged between 5% and 60%.

 - Risk.net (June 2001)


A recent survey of financial institutions has found that most are concerned with credit risk but are not accounting for liquidity risk...Many of the firms are also not applying risk-adjusted methods to allow for a more efficient distribution of capital...the survey [ Economic Capital Survey 05/01 ] which was conducted by Capital Market Risk Advisors..."It's purely based on attitude whether they use the risk-adjusted return method or not," says Leslie Rahl, president of CMRA

- Risk.net (June 2001)


Leslie Rahl, president of Capital Market Risk Advisors in New York, told the group that too many people are becoming mesmerized with value-at-risk (VaR) and other quantitative techniques. Rahl agrees that these tools are valuable. But she thinks that we will look back on them 10 years from now with the same amusement which "state-of-the-art" approaches from the 1980s now inspire. Rahl pointed out that the quantitative part of risk management represents only about one third of a comprehensive risk management programme. "Senior managers - with practical wisdom -definitely need to get involved in helping to set the assumptions behind some of these complex models," she said.

- Euromoney (November 1999)


According to CMRA's Rahl, plan sponsors should be aware of violations of investment guidelines. One common problem is an outside manager who fails to report losses. Says Rahl, "Investment guidelines are often unmonitored by compliance staff and managers override limits." How many trades should be monitored? "That depends. You could monitor every trade if you had the resources. What's more important is to remember the 80/20 rule: 80% of the risks probably come from 20% of the trading. High volume, standardized transactions don't cause operational risk; it's transactions outside the system, the low volume, high impact trades that you should watch."

- Alert Investment Risk (November 1999)


In response to the proposition for a clearinghouse that matches trades and guarantees that all contracts are honored, "It's been talked about for a long time. "  But the idea, she adds, "hasn't gone anywhere because of dealer resistance -- the costs and the complexities in agreeing on what something can be valued at." - Leslie Rahl on Regulating Derivatives

- Derivatives Strategy (December 1998)


VaR does not demonstrate the worst-case scenario

- Derivatives Week (January 1997)


VaR models contain inherent flaws. The biggest glitches surface on days when markets break free of normal patterns, smashing the neatly calibrated VaR volatility and correlation barriers. In recent months convulsions have racked both the CMO and structured-note markets, says Leslie Rahl, a risk consultant and a partner at Capital Market Risk Advisors: "During those market dislocations, the models Wall Street ran couldn't get a fix on what the value of the position was, let alone how much the value at risk was."

- Institutional Investor (February 1995)


Top